Calculate your gap, map your strategy, and build with clarity.
Takes 3 minutes. No sign-up required.
"I have SGD 500,000 — how should I allocate it?"
Most retirement conversations start here. But allocating assets well does not automatically answer the harder question: how much cashflow will they actually produce, and for how long?
"I need SGD 4,000 a month — where does it come from?"
How much to top up CPF, how much into SRS, how much to hold as a buffer — these depend on your cashflow need, not just your asset size. The sequence matters as much as the amount.
"Most people are solving one. A complete retirement plan has to answer both."
It has to generate cashflow — income that arrives regularly and covers essential spending without forcing you to decide each month what to sell. And it has to protect an asset base — a pool that gives you flexibility, resilience, and the ability to handle what you cannot predict. Most plans focus almost entirely on building the second, and treat the first as something that will sort itself out. It rarely does.
"It is the difference between feeling retired and feeling as if you are slowly running out."
A mental model for understanding how each part of your plan contributes — and where the gaps appear.
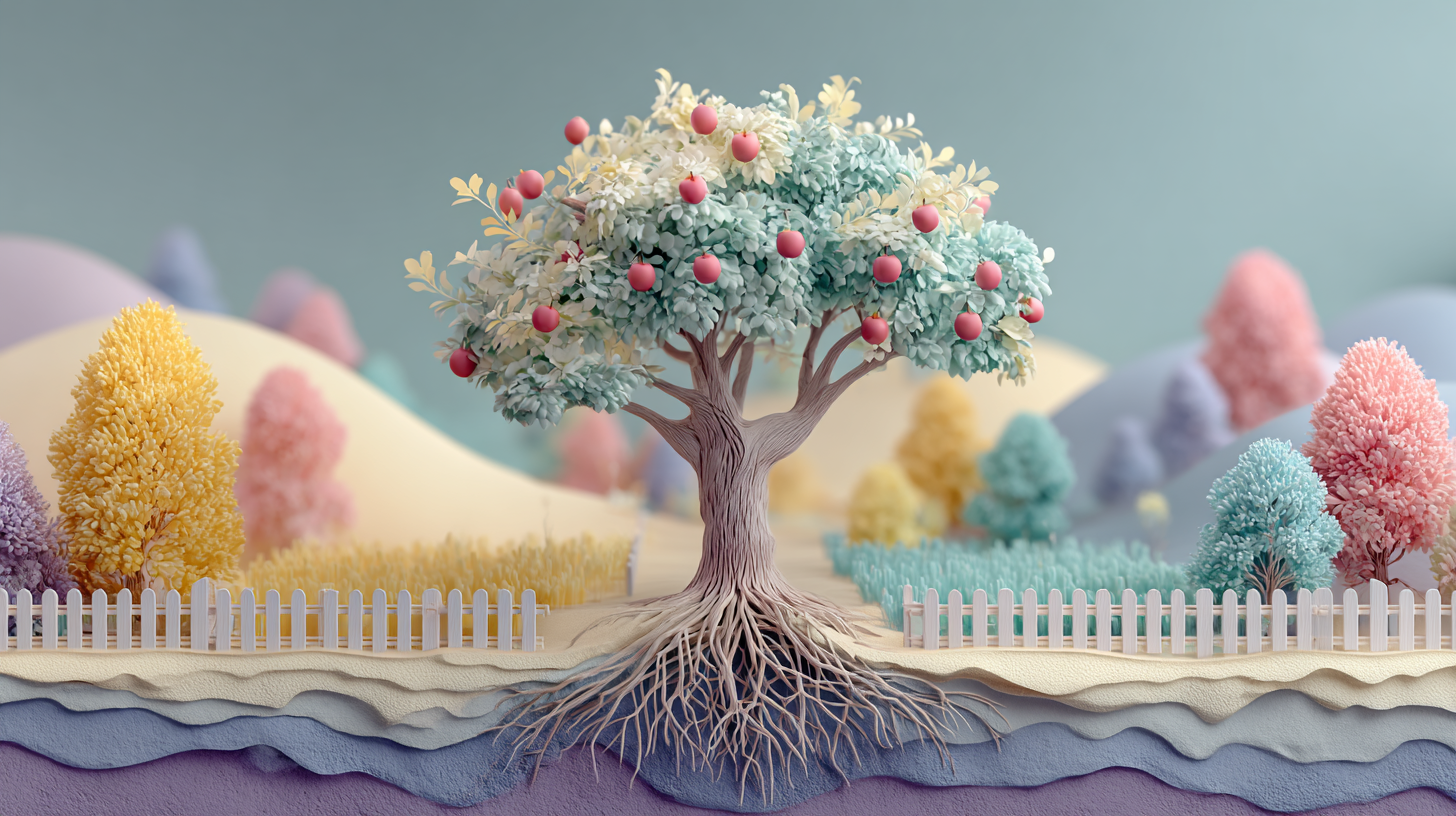
CPF LIFE feeds the cashflow floor directly — government-backed and lifelong. SRS is deployable capital: where it lands depends on how you invest it.
Explore → FenceCash buffer, SSBs, and insurance coverage. Protects the asset base from forced decisions.
Explore → TrunkStructured payouts from insurance and annuity products. Predictable regardless of markets.
Explore → FruitsMarket-linked returns — added only after the cashflow floor is already secure.
Explore → LandIlliquid but powerful. Requires deliberate planning to convert into income or flexibility.
Explore →See your numbers — not projections built on assumptions someone else made for you.
What your existing CPF, policies and assets will generate at retirement.
The monthly amount you actually need, based on your lifestyle and goals.
The shortfall you need to close — and the timeframe you have to close it.
No product push. No email gate. Clarity first.
This site is written and maintained by one person — Mia Ong, ChFC®/S, a financial adviser representative with Phillip Securities Singapore, in financial services since 2011.
How this site works, credentials, and how to reach me →RetireMap gives you a clear picture of your retirement cashflow in 3 minutes. No product pitch. No email required.
Start RetireMap →A capital parking tool. Not a retirement income solution.
Fixed-return instruments with limited availability and short opening windows. Suitable for assets that need a home while you plan the next step. This sits outside the core retirement planning journey.
Flagship series: Singlife Secure Saver — 11 tranches since 2020, cash or SRS eligible.
View Latest / Register →